From smartphones to power electronics in electric cars and medical technology: virtually every industry, every service sector and every economic activity today relies on electronic circuits and, consequently, on semiconductors. Like most countries, Switzerland is dependent on other countries for these, particularly the US and Taiwan. The Covid-19 pandemic highlighted just how vulnerable this makes the country: when chips became scarce, Swiss companies were soon unable to deliver any more machine tools. “Almost all of Switzerland’s economic value creation depends on semiconductor components from abroad,” says Adriaan Spierings, head of the Semiconductors division at the industry association Swissmem.
At the same time, Switzerland holds a number of trump cards in the international semiconductor market. Around 200 players – an estimated 160 to 180 companies as well as several research institutions – employ some 20,000 people in the country. Some of them manufacture equipment and components used in chip production worldwide, including by the industry’s major players. Others produce specialised chips and are among the world’s leaders in their field.
Their strengths lie consistently in niche areas: in photonics, where information is transmitted via light rather than electrons; in semiconductor materials beyond silicon, such as silicon carbide or gallium arsenide; and in very small, precise and energy-efficient circuits, for example for sensor technology or implantable medical devices. Swiss companies do not serve a mass market like TSMC, Samsung or Intel – but they are very successful in global niche markets. Moreover, this position is difficult to challenge: “The manufacture of a chip is highly complex and relies on years of development work. It cannot simply be copied,” emphasises Jürg Leuthold, Professor of Photonics and Communications at ETH Zurich and Work Package Leader for the SwissChips funding initiative.
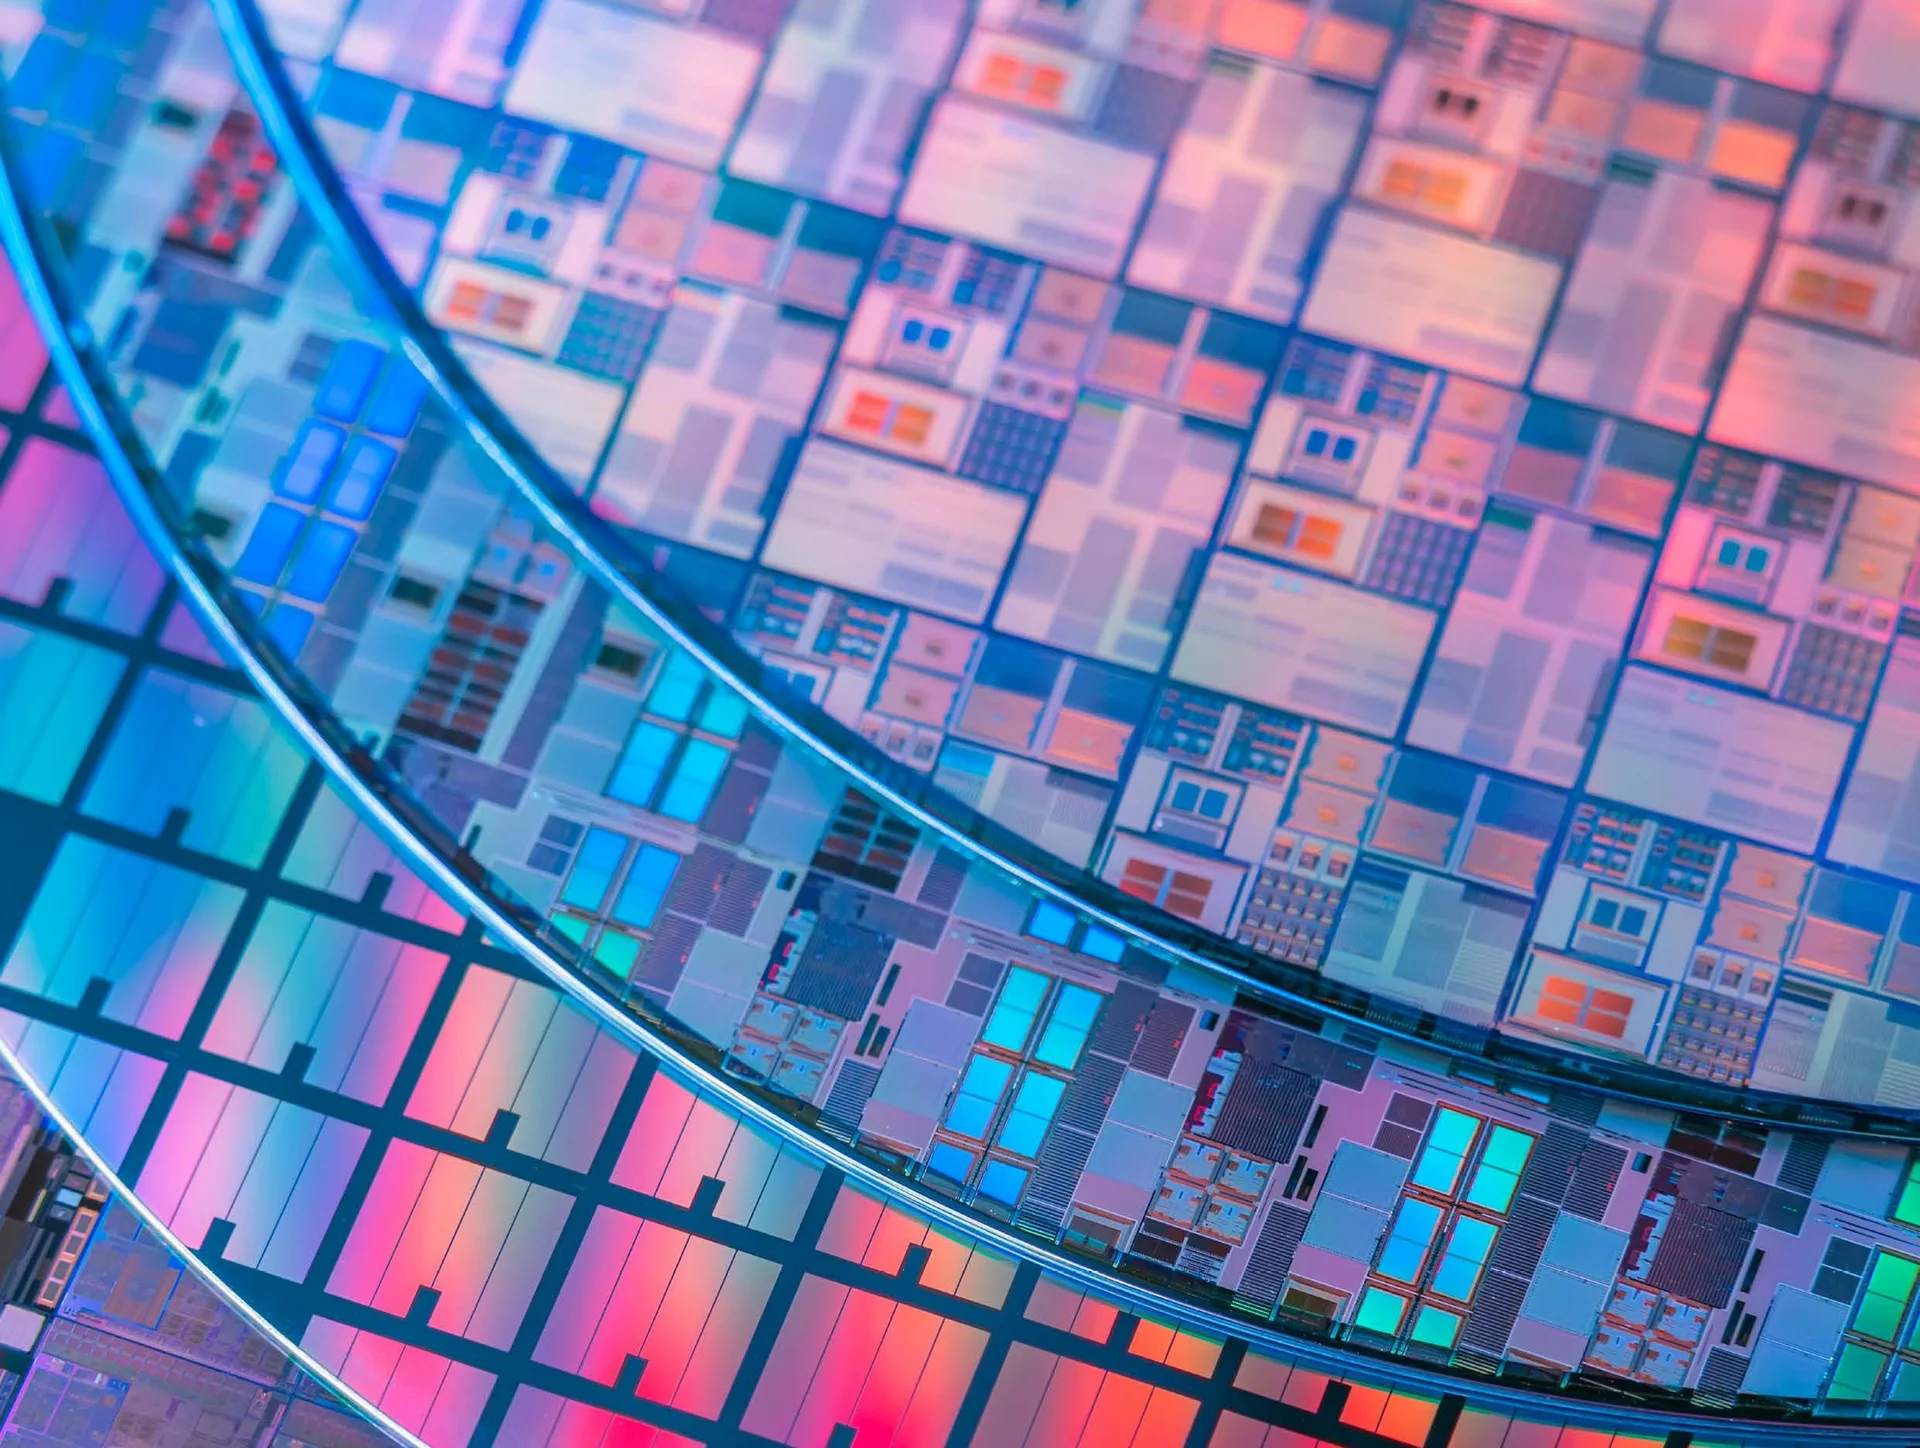
Yet this is precisely where the greatest weakness lies. The manufacture of chips – whether for research or industrial production – requires cleanrooms that are many times more dust-free than an operating theatre, as well as specialised and expensive equipment for what are often 350 or more process steps. Although there are several cleanrooms in Switzerland – for example at ETH Zurich, EPFL, the Paul Scherrer Institute, CSEM and the University of Applied Sciences of Eastern Switzerland – they are small and fragmented. Many companies therefore design their chips in Switzerland but have them manufactured abroad at high cost.
A partnership between ETH Zurich and Empa, supported by Swissmem and several companies, aims to address this with the FabLab project: a shared cleanroom that covers the entire value chain and is open to companies on a non-profit basis under a pay-per-use model. “Many other countries operate such centralised cleanrooms, and they have proven to be one of the chip industry’s global success factors,” explains Leuthold.
Interactive infographic
Chip manufacturing is highly complex and, especially in industrial production, globally interconnected. It is not unusual for chips to travel around the world several times from the start of production to completion.
Select one of the five steps to learn more.
Use the arrow keys to move between the steps.
Even the design of a new component requires extensive expertise and financial resources. In some cases, researchers and companies have to develop new software specifically so that they can create a design for products based on new materials and technologies.
The manufacturing processes for new semiconductor components must first be developed. This development, and later the many production steps, require materials with specific properties as well as specialized equipment in cleanrooms, both for chip fabrication and, for example, for supplying and monitoring process gases.
The components are produced using chemical and physical processes in long process chains that must be developed and tested over many years.
The components themselves must also be tested and characterized after manufacturing. This requires specialized measurement methods and equipment.
Finally, the new components must be connected with other components, for example by integrating them into a computer board. Only then can the technology be used industrially and made accessible to a broad market.
The second bottleneck is the shortage of skilled workers. The higher education and start-up scene is highly mobile; researchers and founders leave if they find better conditions elsewhere. Added to this is international pressure: the US is investing 50 billion dollars in its own chip industry, Japan 65 billion, whilst the EU is supporting semiconductor start-ups with a total of 43 billion euros. Switzerland does not have a direct industrial support scheme – so Swiss companies are fighting on an uneven playing field. With the SwissChips initiative , the federal government has at least allocated 30 million Swiss francs for national semiconductor funding, initially limited to three years, and with the ‘Swiss Chip Strategy’ , the Federal Council has identified key areas for action by 2026.
Open-access cleanroom infrastructure: A central FabLab, accessible to universities, start-ups and companies, pools expensive equipment, shortens development cycles and reduces research and development costs.
Training and skilled workers: Additional semiconductor professorships and attractive conditions ensure that expertise developed in Switzerland also contributes to value creation here.
Pilot projects rather than direct payments: Swissmem does not advocate subsidies for individual companies, but rather pilot schemes and access to suitable facilities and funding, so that promising developments can be industrialised in Switzerland.
A consistent niche strategy: Photonics , alternative semiconductor materials and energy-efficient circuits are the fields in which Switzerland can remain indispensable on the international stage.
International connectivity: Access to markets and research programmes, resilient supply chains and an attractive regulatory framework secure Switzerland’s position within the global ecosystem – not least as a bargaining chip in negotiations, for example on tariffs.
Switzerland will not compete in the global semiconductor market through mass production. Its success depends not on the size of its factories, but on its ability to combine research, talent, infrastructure and industry into a high-performing innovation ecosystem. If it succeeds in doing so, Switzerland can strengthen its technological sovereignty and occupy an indispensable position in global value chains.
This factsheet provides an overview of the Swiss semiconductor industry: its dependence on foreign suppliers, its strengths in highly specialised niches, and the bottlenecks that are holding back its further development. It highlights the key areas for action that are crucial for Switzerland as a semiconductor hub.
It comprises an estimated 160 to 180 companies as well as several research institutions – a total of around 200 organisations employing some 20,000 people. Swiss exports in the ‘machinery and electronics’ sector amounted to 32.1 billion Swiss francs in 2024, whilst imports totalled 32.9 billion Swiss francs (source: Federal Office for Customs and Border Security, BAZG).
In niche areas: photonic chips, semiconductors made from materials other than silicon – such as silicon carbide or gallium arsenide – and very small, precise and energy-efficient circuits. Added to this are companies that supply equipment and components for global chip manufacturing, and a high-calibre research landscape from which start-ups are continually emerging.
Chip manufacturing requires cleanrooms equipped with specialised, expensive machinery for what are often 350 or more process steps. In Switzerland, the existing cleanrooms are small and fragmented, which makes it costly for each individual operator to adapt them on an ongoing basis to new processes. Many companies therefore design their chips here and have them manufactured abroad for a high fee.
A joint initiative by ETH Zurich and Empa, supported by Swissmem and several companies. The aim is to establish a shared cleanroom that covers the entire value chain of semiconductor production and is open to companies on a pay-per-use basis at non-profit rates.
Tensions between the US and China are leading to a partial fragmentation of the semiconductor ecosystem. Numerous countries are investing tens of billions in their chip industries, whilst Switzerland has no direct industrial support schemes. Through the SwissChips initiative, the federal government has allocated 30 million Swiss francs, limited to a period of three years.
To decision-makers in industry, trade associations, research and politics who are involved with Switzerland as a centre for the semiconductor industry, technology transfer and security of supply.
It was written by Dr Santina Russo and Annika Müller on behalf of the SATW and is based on interviews with five experts from the fields of research and industry.
| Role | Title + Name |
|---|---|
| Editorial staff | Esther Lombardini, Stefan Scheidegger |
| Text by | Annika Müller, Santina Russo |
| Expertise | Christofer Hierold, Jürg Leuthold, Heike Riel, Johannes Schumm, Adriaan Spierings |
| Concept | Ester Elices, Peter Seitz |